
“Grab the bucket!” my dad would say, as a summer storm slammed into my South Jersey childhood home.
After years of the same routine, I knew the drill.
At the first sign of a thunderstorm, I’d run, grab a bucket, and place it under the far corner of the kitchen (to the right of the sink) where it would catch the rainwater pouring in through the recess lighting. Before I could get to the corner of the kitchen, I’d have to gently remove the kitchen chair that was propped up against the dishwasher (to hold the broken dishwasher door in place). If the door opened, the dishwasher didn’t run.
The storm would eventually subside and I would head outside to find something to do.
I’d open up the garage where I’d find mountains of trash bags and plastic bins full of used clothes, all with the end destination of the local Goodwill dropoff center. That’s where my parents would exchange our old, tattered clothing for an annual tax deduction on April 15. The only tax I knew back then was the extra money I had to dish out for New Jersey sales tax on the half gallon of Wawa Peach Iced Tea I would get every day.
As I grew up, I started to understand more and more of what was secretly going on under the heaping piles of mothballed clothing and buckets of rainwater from the hole in the roof.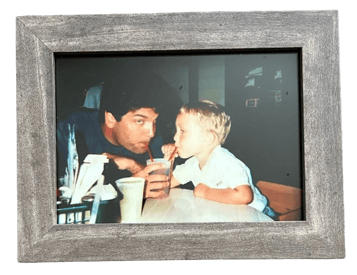
It was fear. Fear that financially, tomorrow wouldn’t be promised. After all, what does any rational person do when they worry they may not have enough for a comfortable future?
They pinch pennies until there is nothing left to pinch.
Just like my parents, they hold off on fixing the dishwasher or roof for as long as they can, because the fear of not having enough down the line trickles into everyday life.
They stress so much about tomorrow that today feels like a room with the walls constantly closing in. I don’t think my dad ever escaped that room of worry. He struggled more than he needed to and it was only in the years after he passed away that I realized it didn’t have to be that way. We could have gotten the dishwasher working, the leaking roof fixed, and seen our garage floor years earlier than we actually did.
Don’t get me wrong, I had the greatest childhood a kid could ask for. I had a new baseball bat or cleats when I needed them. I remember having lots of fun at my birthday parties. I grew up with love around me and I’m intent on giving my own young son the same.
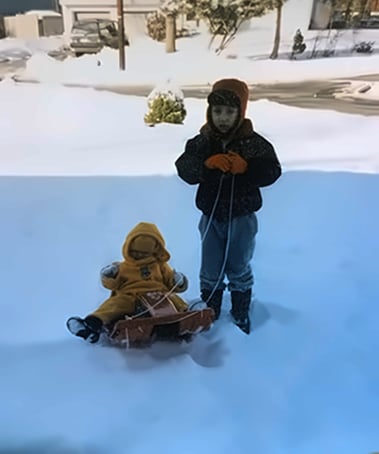 However, growing up also means having conversations about money. And as hard as you might try, the worries can filter in. How am I going to pay for college, that first car, or a home? How am I going to get from where I am today to where I want to be, while enjoying life the way I want?
Questions like that inspired me to become a financial advisor.
When my dad passed away, my mom had a pot of cash and a lot of her own questions. Top of the list was, “How long is this money going to last?” She didn’t know and felt far more comfortable stuffing that money under the mattress than bringing it to a professional. Up until then, my parents knew a lot about risk and uncertainty, but they had very few tools to overcome their fears.
I think we all face those fears to some degree or another. Life is full of uncertainty. Some people ease it by waiting for a tomorrow that may never come, while others do everything they can to avoid thinking about the future.
I recently sat down with a client who reminded me a lot of my parents. They had the same fears about the future, but instead of socking every dollar earned under a mattress, they were buying the most expensive mattress they could find. And the most expensive car. And the most expensive house. They had a big expense budget and multiple countries on the travel “bucket list.”
Only caveat? The current back of the napkin financial plan that they had written up on their own wasn’t lining up with what they wanted to do. There were red flags all over the place. So, we helped them budget. We adjusted their asset allocation to reflect a future that was more realistic.
But more than that, I got to know them on a deeper level. I grew up with questions all around me, so I knew that by understanding what my clients wanted to accomplish we would arrive at the plans we needed to build.
Every client I’ve ever worked with is carrying their own version of a bucket under a leak, a broken dishwasher, or a garage that’s bursting at the seams, whether they know it or not.
Some are so afraid of the financial storm that they never get around to fixing the roof or clearing the bags of clothes out. Others are so focused on the house and how to “keep up with the Joneses” that they forget to check if the plumbing works or if the foundation is sturdy.
My job isn’t to tell anyone that they’re wrong.
There’s an avenue for everything. It’s an outlook that’s helped me see the whole structure clearly, the income, the expenses, the risk, the time horizon—but most importantly the person who’s doing their best to make it all work.
It’s about getting them from where they are today to where they want to be tomorrow, while enjoying the ride.
My parents never had someone sit across from them with a plan. They had a bucket, a chair against a broken dishwasher, and a garage filled to the brim with good intentions.
I wish I could go back in time and help them empty every bucket of worry they were carrying around. Whether you’re stretching every dollar or spending every dime, the question remains: does your plan get you where you want to be?
Zack Renna is a client of TradePMR. No compensation was paid to Mr. Renna for this article. This article reflects this client's experience. Your experience may vary.